Copyright © LYDIAN FINANCIAL SERVICES PTY LTD 2026. All Right Reserved.
Two borrowers can have similar incomes, deposits and loan amounts, yet receive very different answers from different lenders.
Two borrowers can have similar incomes, deposits and loan amounts, yet receive very different answers from different lenders. One lender may decline an application, another may approve it with additional conditions, and a third may accept it at a higher interest rate.
These differences reflect how lenders are regulated, how they obtain their funding and which risks they choose to accept. Understanding those differences is particularly valuable for self-employed borrowers, whose financial position may require more interpretation than a payslip can provide.
What are the three tiers?
For this article, the Australian home lending market can be grouped into three broad categories:
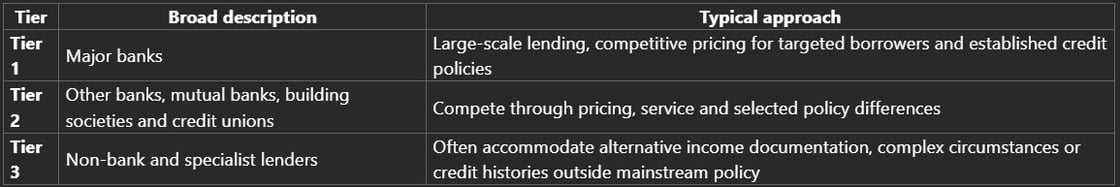
These are industry descriptions, rather than formal regulatory classifications. Some non-banks compete directly for straightforward, prime borrowers, while some smaller banks operate conservative lending models. “Third tier” does not automatically mean poor credit quality or expensive lending.
The significant regulatory distinction is whether the lender is an authorised deposit-taking institution, or ADI. Major banks and smaller ADIs operate within APRA’s banking prudential framework. A smaller bank does not receive a lighter serviceability framework simply because it is described as second tier. APRA: Banking
APRA and ASIC perform different roles
APRA focuses on the financial strength of regulated institutions and the stability of the financial system. Its banking framework addresses matters including capital, liquidity and credit risk.
ASIC administers the consumer credit framework, including responsible lending obligations. For regulated home lending, lenders must make reasonable inquiries about the borrower’s financial circumstances and objectives, take reasonable steps to verify their financial situation, and assess whether the loan is unsuitable. These obligations apply to both bank and non-bank credit providers where the National Credit Act applies. ASIC: Responsible lending
Consequently, non-banks can have different lending policies without being exempt from consumer protection requirements. Their flexibility comes from a different prudential position, funding arrangements and risk appetite—not permission to disregard affordability.
Serviceability: why borrowing capacity changes between lenders
Serviceability measures whether the borrower can meet repayments after allowing for expenses, existing debts and a margin for adverse changes.
For ADIs, APRA’s standard mortgage serviceability buffer remains three percentage points above the loan interest rate. A loan charging 6% would therefore ordinarily be assessed at at least 9%, with the lender’s own assessment floor potentially producing a higher rate. APRA confirmed the three percentage point setting in its May 2026 review. APRA: Current macroprudential settings
However, the interest rate buffer is only one part of the calculation. Lenders can produce different results because they treat income and commitments differently. Their policies may vary in how much rental income they accept, how they recognise overtime or bonuses, how they assess business earnings, and how they calculate existing debt repayments.
This is where policy selection matters. A borrower may qualify with one bank because that bank recognises more of their sustainable income, even though both banks apply the same regulatory interest rate buffer.
Non-ADI lenders are not automatically subject to the ADI-specific three percentage point requirement. They may use different buffers, floors and assessment methods, subject to responsible lending, their funding conditions and any applicable regulatory measures. APRA also has reserve powers concerning non-ADI lending where financial stability risks warrant intervention. APRA: Macroprudential Policy Framework
A lower buffer does not necessarily mean greater borrowing capacity: a higher product rate can offset the difference.
What are “plug rates”?
“Plug rate” is informal terminology. Here, it means the rate or repayment assumption a lender inserts into its serviceability calculation, particularly when assessing existing commitments.
For example, the repayment a lender uses for an existing mortgage may differ from the amount currently leaving the borrower’s account. Credit cards and other facilities can also attract assumed commitments under the lender’s assessment policy.
These assumptions can materially affect borrowing capacity. Comparing lenders therefore requires examining the entire serviceability calculation, rather than focusing solely on the advertised rate or buffer. APRA’s mortgage guidance addresses the need to assess income, expenses and debt commitments prudently. APRA: Residential Mortgage Lending guidance
There is also a separate portfolio constraint. From February 2026, APRA limited ADIs’ new lending at debt-to-income ratios of six times or more to 20% of new owner-occupied lending and, separately, investment lending, subject to specified exemptions. This is a portfolio limit rather than an automatic prohibition on an individual borrowing above six times income. APRA: Activation of debt-to-income limits
LVRs: flexibility depends on the whole application
The loan-to-value ratio, or LVR, compares the loan amount with the lender’s accepted property value. An $800,000 loan against a property valued at $1 million has an 80% LVR.
Higher LVRs leave less protection against falling property values and recovery costs. Lenders therefore consider LVR alongside income reliability, credit history, property type and location. For ADIs, APRA’s capital framework also differentiates residential mortgage exposures according to relevant risk characteristics, including LVR and documentation standards. APRA: APS 112
Flexibility is rarely available equally across every feature of a loan. A lender willing to accept alternative income documentation may require a larger deposit. Another may accept a smaller deposit but require conventional income evidence and a strong repayment history.
A specialist lender can therefore be more flexible on income verification while being more restrictive on LVR. The trade-off depends on the combination of risks.
Waivers: lender policy has limits
A waiver can mean several different things: an exception to an internal policy, a reduced fee, a concession on documentation, or a waiver of lenders mortgage insurance.
LMI commonly applies above 80% LVR and protects the lender if the borrower defaults. It does not protect the borrower. Whether it is required depends on the lender, product and circumstances.
Moneysmart: Lenders mortgage insurance
An LMI waiver does not automatically waive serviceability, valuation requirements or other approval conditions. Similarly, approving a policy exception does not remove the lender’s legal obligations.
APRA recognises that banks can make limited, prudently managed exceptions to policy, including in some refinancing circumstances. These decisions require appropriate assessment, oversight and monitoring; they are not a general entitlement to a lower assessment buffer. APRA: Guidance on exceptions
The practical question is therefore: exactly which requirement is being waived, and which requirements still apply?
Pricing and funding: why flexibility can cost more
Banks can fund lending through customer deposits as well as wholesale markets and other sources. Non-banks cannot raise deposits in the same way and commonly rely on warehouse facilities, securitisation and institutional investors.
A warehouse facility funds loans before they are packaged into securities and sold to investors. The Reserve Bank explains that these facilities are commonly supplied by banks themselves. This means a non-bank may have considerable control over its customer policy while still operating within conditions imposed by its funding providers. RBA: Non-bank lending in Australia
The price of a home loan must cover funding costs, expected credit losses, operating expenses and the return required by capital providers. Applications requiring specialist assessment can also involve more work.
This helps explain why additional flexibility may attract a higher rate or fee. Funding markets matter too: the RBA has documented how weaker demand for some mortgage-backed securities increased non-bank funding costs, and how warehouse conditions impose discipline on lending standards. RBA: Financial stability risks from non-bank finance
Nevertheless, pricing does not follow a fixed tier hierarchy. A non-bank targeting straightforward borrowers may compete aggressively on price, while a bank may charge more for a loan outside its preferred segment.
Self-employed income: alternative verification is a different evidence pathway
Self-employed borrowers can have sustainable earnings that are difficult to demonstrate through standard documents alone. Tax returns may describe an earlier trading period, while income can flow through a company, trust or partnership.
The assessment must establish what income is sustainable and available to meet personal commitments. Business turnover is not personal income: business expenses, tax, liabilities and ongoing working capital needs still matter.
Depending on the lender and product, alternative verification may include:
For example, Pepper Money publishes an alternative documentation pathway using a financial position declaration together with business bank statements, lodged BAS or an accountant’s letter, subject to its eligibility and assessment requirements. This illustrates one lender’s approach rather than a universal industry standard. Pepper Money: Alternative documentation
Banks may also offer policies accommodating self-employed borrowers, but the permitted evidence and treatment of earnings differ between institutions. A borrower should therefore compare documentation pathways before assuming specialist lending is necessary.
Crucially, “alt doc” or “low doc” does not mean that income can go unverified. ASIC has expressly stated that lenders must verify income regardless of whether a loan is described as low doc. ABN registration establishes the existence of a business registration; it does not establish how much the borrower earns. ASIC: Review of low-doc home lending, ASIC: Review of low-doc credit assistance
Choosing the lender whose policy fits
Australia’s three broad lender tiers exist because borrowers need different forms of assessment, and lenders have different funding models, operating costs and appetites for risk.
The strongest application is not necessarily the one presented to the most flexible lender. It is the one presented to a lender whose policy properly recognises the borrower’s sustainable income, accepts the proposed security and offers appropriate terms.
For a self-employed borrower, the comparison should consider the accepted income evidence, serviceability assumptions, maximum LVR, available exceptions and total loan cost together. An approval based on alternative documents may solve a real problem, but its value depends on whether the repayments and conditions remain workable.
The central distinction is between regulatory requirements, lender policy and funding conditions. Understanding all three explains why lenders can reach different decisions about the same borrower—and why flexibility usually involves a considered trade-off.
Australian regulatory settings checked as at 20 October 2026. Individual lender policies and product eligibility can change.
Download the PDF to read later or pass on to a client.
If something here applies to you or a client, book a free consultation and we will work through what it means in practice.
Book a free consultation