Copyright © LYDIAN FINANCIAL SERVICES PTY LTD 2026. All Right Reserved.
Australia’s major property markets have entered a distinctly different phase. After several years in which rising property prices dominated the conversation, the latest Cotality housing data shows Sydney, Melbourne and Brisbane are now all experiencing falling dwelling values.
Australia’s major property markets have entered a distinctly different phase.
After several years in which rising property prices dominated the conversation, the latest Cotality housing data shows Sydney, Melbourne and Brisbane are now all experiencing falling dwelling values.
But underneath that headline, the three markets are behaving very differently.
Sydney and Melbourne are experiencing a more established correction, particularly at the premium end of their markets. Brisbane, meanwhile, has started to retreat from recent highs but remains substantially ahead of where it was a year ago.
For borrowers, property investors and financial advisers, this is important.
A softer property market isn’t necessarily a reason to stop making decisions. It can be a reason to review your strategy.
The Australian market has moved into a correction
National dwelling values fell 3.1% over the three months to August 2026, although values remain 2.7% higher over the year.
The weakness is concentrated in the capitals. Combined capital-city values declined 3.7% over the quarter, compared with only 1.2% across regional Australia.
The divergence between Australia’s three largest east-coast cities is particularly interesting:
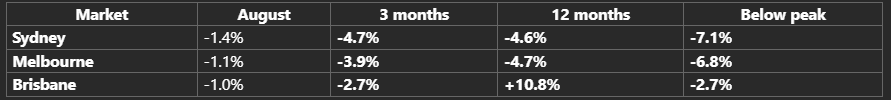
The numbers tell us that this is not one Australian property market.
Sydney: the correction is creating a different buying environment
Sydney is currently experiencing the largest adjustment of the three cities.
Dwelling values fell 1.4% in August, are down 4.7% over the quarter and 4.6% over 12 months. Sydney property values are now 7.1% below their February 2026 peak.
Perhaps more significant is where the weakness is occurring.
Cotality’s analysis shows higher-value Sydney dwellings have led the market lower. The upper quartile of Sydney houses has already fallen by more than 10% during the downturn.
Over the latest quarter, Sydney’s dwelling-value segments fell approximately 2.1% at the lower end, 4.2% through the middle and 5.7% across the highest-value quartile.
That is particularly relevant to Lydian clients.
Our clients are often not simply looking for the cheapest mortgage. They may be upgrading their home, building an investment portfolio, restructuring debt, purchasing through a trust or SMSF, or considering how property fits within a broader wealth strategy.
For a financially strong borrower, a 5–10% adjustment in premium property values can potentially be more significant than a relatively small change in the cost of finance.
The question becomes less:
“Should I wait for interest rates?”
and more:
“Does the change in property values create an opportunity to acquire the right asset at a better price?”
Melbourne: Australia’s major-market value opportunity?
Melbourne is equally interesting.
Values declined 1.1% in August, 3.9% over the quarter and 4.7% over the year. Melbourne dwelling values are now 6.8% below their March 2022 record high.
That last statistic deserves attention.
Unlike Brisbane, where values remain 10.8% higher than a year ago, Melbourne has effectively experienced a prolonged period of price underperformance.
For investors and owner-occupiers with a longer investment horizon, that changes the conversation.
Melbourne isn’t necessarily a market to avoid because prices have been weak. It may increasingly become a market where relative value is re-emerging.
The upper end has again experienced the greatest quarterly decline: the Cotality value-segment data shows falls of approximately 1.3% for the lower quartile, 3.3% for the middle and 5.3% for the upper quartile.
For buyers looking at quality Melbourne property, particularly established homes and premium locations, that widening price adjustment deserves consideration.
Brisbane: cooling, rather than collapsing
Brisbane tells a very different story.
Values have fallen 2.7% over the latest quarter, but remain an impressive 10.8% higher than a year earlier. The market is only 2.7% below its May 2026 record high.
So Brisbane’s current weakness needs context.
Sydney and Melbourne are correcting after longer periods of weaker performance. Brisbane is retreating from a very strong growth cycle.
That distinction matters to investors.
It suggests the Brisbane conversation may increasingly move from:
“How quickly will prices rise?”
to:
“Which assets and locations still represent value after a significant period of growth?”
Brisbane rental fundamentals also remain comparatively strong. Rents increased 6.4% over the year to August, compared with 5.0% in Melbourne and 4.8% in Sydney.
Buyers are gaining negotiating power
Another major theme emerging from the September data is the changing balance between buyers and sellers.
Nationally, homes are taking a median 39 days to sell, compared with 28 days a year earlier.
Sydney properties are taking around 45 days, Melbourne 43 days, while Brisbane is around 35 days.
Vendor discounts are also increasing. Across the combined capitals, the median discount reached 4.2% over the three months to August — the largest discount in at least two years.
And there is more stock for buyers to consider.
Total listings nationally have risen to approximately 139,167, which is 18.1% higher than a year ago and 2.2% above the five-year average.
Cotality attributes the increase partly to reduced buyer demand and longer selling times.
The city-level numbers are particularly revealing.
Total listings compared with the equivalent period last year are approximately 11.3% higher in Sydney, 14.2% higher in Melbourne and 53.3% higher in Brisbane. At the same time, fewer new properties are being listed in Sydney and Melbourne, while Brisbane is seeing increased new-listing activity.
In simple terms:
Buyers have more choice, properties are taking longer to sell, and sellers are increasingly having to negotiate.
Auctions are reinforcing the same message
Auction markets tell a similar story.
The four-week average capital-city auction clearance rate was just 49.5% at the end of August, having remained below 50% since early June.
Sydney and Melbourne clearance rates had improved slightly but remained well below average. Brisbane’s four-week clearance rate was particularly weak at 32.8%.
Cotality notes that the high proportion of properties being passed in suggests buyer and vendor price expectations remain misaligned.
That is precisely the type of market in which prepared buyers can have an advantage.
The opportunity isn’t just about property prices
At Lydian, we believe property decisions should rarely be considered independently of lending strategy.
A falling market can create opportunities, but only where the debt structure supports the client’s broader financial position.
Before purchasing, upgrading or investing, we believe borrowers should understand:
This becomes particularly relevant because property remains Australia’s dominant household asset.
Australian residential real estate is worth approximately $12.2 trillion, compared with $4.8 trillion held in superannuation and $3.7 trillion in Australian listed equities. Housing represents approximately 56.8% of Australian household wealth, with around $2.6 trillion of outstanding mortgage debt.
Property and debt strategy therefore shouldn’t operate separately from financial planning.
What does this mean for borrowers?
Our reading of the data is that the opportunity is becoming increasingly city-specific.
Sydney is moving deeper into a correction, particularly at the premium end. For strong borrowers looking to upgrade or acquire quality property, improving negotiating conditions deserve attention.
Melbourne may increasingly present a relative-value opportunity. Values remain below their 2022 peak and the premium segment has experienced meaningful price adjustment.
Brisbane remains structurally stronger based on the past year’s performance, but the market is cooling rapidly. Investors should be increasingly selective rather than assuming the extraordinary growth of recent years will simply continue.
Across all three cities, one common theme is emerging:
That means having finance assessed before negotiating, understanding borrowing capacity, structuring debt correctly and knowing exactly what price represents value for your circumstances.
From mortgage rate to property strategy
The next phase of Australia’s property cycle may require a different approach from borrowers.
For several years, rapidly rising prices meant buyers often focused on simply securing a property.
In a softer market, the focus can shift towards negotiation, asset selection, finance structure and strategy.
For Lydian clients and our financial planning partners, that’s an important distinction.
We don’t believe the starting question should simply be:
“What’s the cheapest home loan?”
It should be:
“What are you trying to achieve with property and debt over the next five to ten years — and how should your lending be structured to help you get there?“
Premium Banking. Lending Strategy. Property.
If you’re considering buying, upgrading, investing or simply want to understand what the changing Sydney, Melbourne or Brisbane property market means for your existing debt position, speak with a Lydian adviser about a Property & Lending Strategy Review.
Source: Cotality Monthly Housing Chart Pack, September 2026. Property and lending strategies should be considered having regard to individual circumstances and, where appropriate, in conjunction with financial, tax and legal advisers.
Download the PDF to read later or pass on to a client.
If something here applies to you or a client, book a free consultation and we will work through what it means in practice.
Book a free consultation